Meta reported third-quarter results on October 21. Revenue beat and the Q4 outlook was above expectations, but margins fell sharply and the company raised the low end of its 2026 capital spending range. The stock fell roughly 3% in morning trading the next day, according to 24/7 Wall St. This follows our earlier preview.
The numbers
| Metric | Q3 2026 | Context |
|---|---|---|
| Revenue | $64.6B, up 26.1% | Above Meta’s $61B to $64B guidance and the roughly $63.3B consensus |
| Net income | $9.86B | After a $9.89B legal charge for a youth-litigation settlement with state attorneys general |
| Diluted EPS | $7.40, excluding the legal charge | Above estimates; analysts had expected about $6.5 |
| Operating margin | about 20% | Down from about 40% a year earlier |
| Capital expenditure | $34.9B | Below the $41B to $42B analysts had expected in previews |
| Free cash flow | negative $2.12B |
Guidance
- Q4 revenue: $73B to $76B, above the consensus of about $73.6B.
- 2026 capex: narrowed to $135B to $145B, with the low end raised from $130B.
- 2026 total expenses: $175B to $179B.
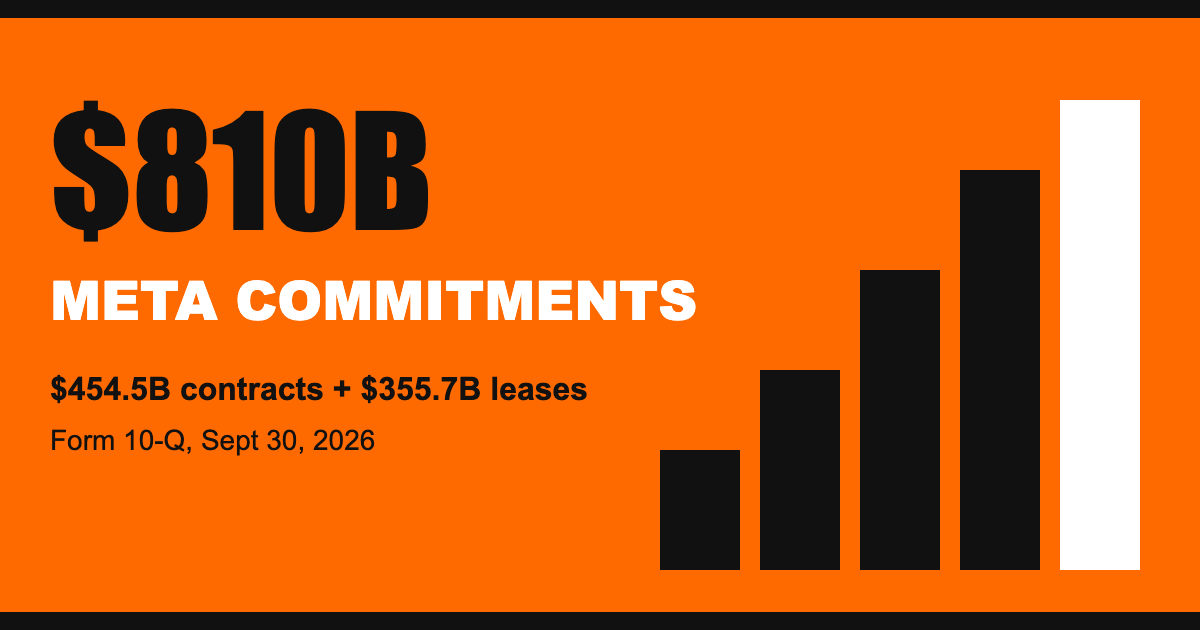
- Commitments: a filing on October 22 showed future spending commitments, mainly for computing power and data centre leases, well above the July level.
2027 signals
Management said Reality Labs losses should narrow to about $15 billion in 2027, from $18 billion to $19 billion in 2026, as investment shifts toward AI. It also said it expects to improve the cost efficiency of its Muse AI agent by more than ten times in the next year, which it sees as necessary for the product to become profitable at scale.
What this tells us
- Demand is not the issue. Revenue growth of 26% is strong for a company of this size.
- Cost is. The margin drop reflects the legal charge and higher infrastructure costs. Excluding one-offs the picture is better, but the infrastructure trend is real.
- The spending range tightened upward. Narrowing from $130B to $145B to $135B to $145B removes the low-spend scenario.
- Quarterly capex came in lower than previews. Spending is lumpy, and commitments rising in the filing suggests the larger outlays are ahead.
Where to be skeptical
- Figures vary by outlet. EPS and net income depend on whether the legal charge is included. Check the company release for the exact basis.
- Pay-off is unproven. Meta has no large cloud business to resell its capacity, so returns must come from ads, engagement and new products such as Muse.
- Legal exposure continues. One report says a New Mexico judge ordered Meta to pay $25 billion under the state’s consumer protection law after a September jury verdict. Meta disputes it and plans to appeal. It is a court order, not money collected.
This article is informational, not investment advice.